


Our Core Services
How Can We Help Aguadilla Clients
For Who We Serve
Many Aguadilla Federal Employees & Professionals Face Challenges
With a long-standing federal and aviation presence, the northwest has a distinct planning need most advisors outside the region don’t specialize in.

Families & Professionals
We help working professionals and families plan for retirement, protect their assets, and prepare for major financial goals, including many current and former federal employees in the area.

Federal & Government Employees
The region’s FERS and TSP participants benefit from planning that treats federal retirement benefits and Puerto Rico tax rules as connected, not separate, decisions.

Business Owners & Self-Employed
Small business owners here need retirement, tax, and insurance strategies coordinated together, we help build that structure from the ground up.
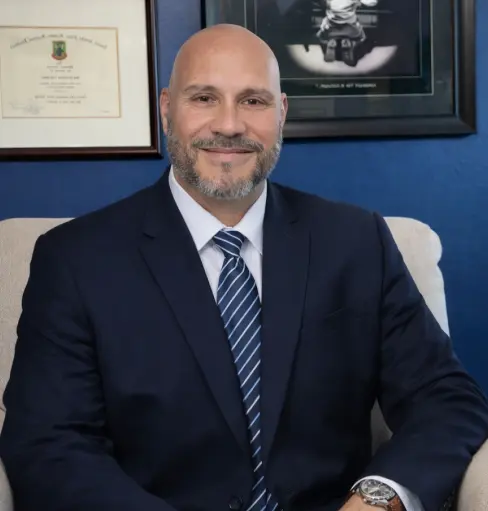
Meet Your Advisor
Credentialed Guidance for the Northwest
Juan L. Aquino
MBA, CPFC®, FRC℠ — Especialista en Planificación Financiera y Contributiva
Aguadilla’s aviation and federal-service community brings FERS and TSP questions to the table, and Juan treats them alongside Puerto Rico tax rules as one plan. He can meet with clients by phone or video, since our only office is in San Juan, and welcomes visits there. Advice is delivered clearly, without pressure and without guarantees of return.
Frequently Asked Questions

