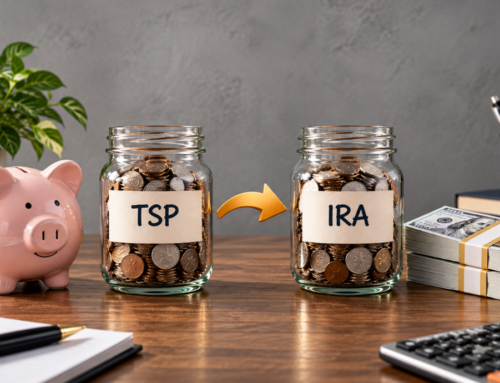
Turning 50 doesn’t feel like a financial milestone the way turning 30 or 40 sometimes does, but it quietly is one, and the decisions made in the next several years carry more weight than the same decisions would have carried a decade earlier or later. It’s the age the IRS starts letting you save more, the age Social Security’s math becomes concrete rather than abstract, and, for a lot of people, the age a parent’s health or a child’s college bill starts competing directly with a retirement account for the same limited paycheck. Confidence about retirement has actually gotten worse recently rather than better: only 61% of workers in the 2026 EBRI Retirement Confidence Survey said they feel confident about having enough money to live comfortably in retirement, a six-point drop from the year before and one of the lowest readings recorded since 2017, according to this analysis of common retirement planning mistakes. For Puerto Ricans in their 50s specifically, that national confidence gap comes layered on top of a dual tax system, a Social Security structure that works differently for federal employees, and a set of local financial pressures mainland retirement content rarely addresses directly.
Mistake One: Treating “I’ll Catch Up Later” as an Actual Plan
The single most common mistake at this age isn’t a bad investment decision; it’s the absence of any decision at all, built on the assumption that the next decade will somehow fix what the previous two didn’t.
Why the Math Gets Harder, Not Easier, With Delay
Not saving enough during the 40s loses compound growth that catch-up contributions in the 50s simply cannot replace at the same rate, since there are fewer remaining years for new money to grow, according to this guide to major retirement planning mistakes. This is the uncomfortable arithmetic behind why “catching up” in your 50s requires saving considerably more aggressively than saving the same total amount would have required a decade earlier.
The Tool the IRS Actually Built for This Exact Situation
The good news is that catch-up contributions exist specifically to address this gap, and 2026 brought meaningful increases worth understanding in detail:
- Workers 50 and older can contribute an extra $8,000 annually to a 401(k) beyond the standard $24,500 limit, bringing the total to $32,500 for 2026
- Workers turning 60, 61, 62, or 63 during the year qualify for an enhanced “super catch-up” of $11,250 instead of the standard $8,000, under a provision introduced by SECURE 2.0, according to this official IRS guidance on catch-up contributions
- IRA savers 50 and older can add an extra $1,100 annually, bringing the total allowable IRA contribution to $8,600 for 2026
Read Also: Roth Conversions in Puerto Rico: When They Work and When Not
Mistake Two: Missing the New Rule That Quietly Changed How High Earners Catch Up
This is a genuinely new wrinkle for 2026, and it catches people off guard specifically because it changes a benefit many high-earning fiftysomethings had relied on for years without thinking twice about it.
The Roth-Only Requirement Nobody Saw Coming
Beginning in 2026, plan participants whose prior-year wages with their employer exceeded $150,000 must make any 401(k) catch-up contribution on a Roth basis rather than a pre-tax basis, a rule finalized by the IRS in September 2025, according to this Kiplinger analysis of the catch-up contribution change. For a higher earner who had counted on that catch-up contribution as a pre-tax deduction to manage their current-year tax bill, this change means paying tax on that portion now instead, a shift that can push a 2026 tax bill up by several thousand dollars for someone who hasn’t adjusted their withholding or estimated payments to account for it.
What This Means Practically for Puerto Rico’s Higher Earners
A handful of practical steps help someone affected by this change avoid an unpleasant surprise at filing time:
- Confirming with an employer’s HR or benefits department whether the workplace 401(k) plan actually offers a Roth catch-up option at all, since a plan without one may not permit catch-up contributions for affected high earners until it adds the feature
- Adjusting current-year withholding or estimated tax payments to account for the loss of what was previously a pre-tax deduction, rather than discovering the gap when a tax return is filed
- Recognizing that the silver lining, tax-free growth and tax-free withdrawals on the Roth catch-up portion, can still be a genuinely good outcome for someone who expects to be in a similar or higher tax bracket during retirement
Mistake Three: Ignoring the Puerto Rico-Specific Layer on Top of Federal Rules
National retirement content, including most of the advice covered so far, assumes a purely federal tax picture, and applying it directly to a Puerto Rico resident without adjustment is itself a mistake worth naming on its own.
Why the Same Federal Numbers Don’t Tell the Whole Story Here
Puerto Rico residents navigate both federal retirement account rules and the island’s own separate tax code simultaneously, and a tax efficient retirement in Puerto Rico strategy built purely around federal catch-up limits and deduction rules, without considering how Hacienda treats the same contributions and eventual withdrawals, routinely leaves real money on the table. This is particularly true for anyone holding a mix of federal-source income, Puerto Rico-source income, and retirement accounts that may be qualified under one tax code, the other, or both.
Self-Employed Puerto Ricans Face Their Own Version of This Mistake
Puerto Rico’s self-employed professionals and small business owners in their 50s often default to a standard IRA without ever comparing it against higher-capacity options genuinely built for this exact situation. A Keogh plan in Puerto Rico structure, a SEP-IRA, or a Solo 401(k) can shelter significantly more income than a standard IRA allows, and for someone in their peak-earning 50s trying to compress a lifetime of saving into a shorter remaining runway, that difference in contribution capacity matters enormously.
Mistake Four: Reacting Emotionally to Short-Term Market Swings
The 50s bring a specific and dangerous temptation: having fallen behind, some savers respond by taking on more investment risk in hopes of a quick catch-up, rather than sticking with a disciplined, time-tested strategy.
Why This Decade Is the Wrong Time to Start Gambling
Reallocating steady, long-term investments in hopes of a big score is precisely the wrong move at this stage, since there’s meaningfully less time remaining to recover from a significant loss than there would have been two decades earlier, according to this 2026 guide to retirement mistakes specific to the 50s. Short-term market swings can also trigger the opposite mistake, panic selling during a downturn, locking in losses that a calmer, longer-term perspective would have avoided entirely.
A Steadier Approach Worth Adopting Instead
A handful of habits help savers in their 50s stay disciplined rather than reactive during periods of market volatility:
- Maintaining a written investment plan and reviewing it during calm periods, rather than making changes reactively in the middle of a market drop
- Keeping catch-up contributions flowing on a consistent schedule regardless of short-term headlines, since consistency matters more than perfect timing over a multi-year horizon
- Working with a financial investment advisor in Puerto Rico to stress-test the portfolio against a genuine market downturn before one actually happens, rather than discovering the plan’s weaknesses during an actual crisis
Mistake Five: Avoiding the Money Conversation With Aging Parents
This mistake is uncomfortable enough that many people simply avoid it entirely, and that avoidance often costs far more than the awkwardness of the conversation itself.
Why This Conversation Belongs in a Retirement Plan at All
Discussing money with aging parents, particularly when the conversation touches long-term care costs or end-of-life planning, feels intrusive to many adult children, but avoiding the topic doesn’t make the underlying financial exposure disappear, according to this 2026 guide to retirement savings mistakes in your 50s. Puerto Rico’s strong multigenerational family culture means this scenario plays out constantly: adult children in their 50s quietly absorbing a parent’s uncovered medical costs, housing needs, or long-term care expenses directly out of what should have been their own retirement contributions.
Questions Worth Asking Before a Crisis Forces the Conversation
A handful of direct questions, asked calmly and without judgment, uncover most of the financial exposure this scenario creates:
- How much has a parent actually saved for long-term care, and what happens financially if that runs out?
- Does an estate plan already exist, and does it reflect the parent’s actual current wishes rather than assumptions made years earlier?
- Is there a realistic risk that supporting a parent’s care will require pulling from a retirement account, and if so, has that risk been built into the retirement plan itself rather than treated as an unexpected emergency later?
Mistake Six: Skipping a Real Healthcare Cost Plan Before Medicare Eligibility
The gap between when many people actually retire and when Medicare eligibility begins at 65 is a financial blind spot that catches even otherwise well-prepared savers off guard.
Why This Gap Deserves Its Own Line Item
Entering retirement without a specific plan for healthcare costs before Medicare eligibility begins can force early retirement account withdrawals, which carry ordinary income tax and, for anyone under 59½, an additional 10% penalty on top of it, according to this overview of common retirement planning mistakes. For Puerto Rico residents specifically, this gap deserves even more careful attention, since health insurance in Puerto Rico options and costs during this pre-Medicare window can differ meaningfully from what generic mainland retirement content assumes.
Mistake Seven: Assuming Work Will Simply Stop on a Specific Date
A growing number of people entering their 50s are planning around an assumption that doesn’t match how retirement is actually unfolding for most Americans today.
What the Actual Data Shows About Working Longer
More than six in ten Americans, 61%, now say they plan to continue working in some capacity as they transition into retirement, whether through part-time work, consulting, or other flexible arrangements, rather than stopping on a fixed date, according to this 2026 State of Retirement Planning survey. Building a retirement plan around a hard stop date, without considering that phased or part-time work might genuinely be part of the picture, either underestimates available flexibility or, for those who assume they’ll simply keep working indefinitely as a backup plan, overestimates how reliable that assumption actually is if health or job market conditions change unexpectedly.
Mistake Eight: Never Actually Running the Numbers Against a Real Plan
Perhaps the broadest mistake underlying everything else on this list is relying on rough estimates, generic online calculators, or comparisons to national averages instead of a plan built around actual, specific numbers.
Why Averages Are the Wrong Benchmark
Comparing a personal retirement balance against national average savings figures by age creates two equally unhelpful reactions: panicking because a balance sits below average, or assuming everything is fine simply because it sits above the median, according to this 2026 analysis of average retirement savings by age. Actual retirement needs depend on income, expenses, debt, tax situation, planned retirement age, expected Social Security and pension income, health, family circumstances, and desired lifestyle, none of which a national average accounts for.
What a Real Plan Actually Requires
A genuine retirement projection, rather than a rough guess, generally walks through several specific components together rather than estimating each one in isolation:
- A realistic withdrawal rate applied to actual account balances; current research points to roughly 3.9% as a reasonably safe starting withdrawal rate for a 2026 retiree drawing from a balanced portfolio over a 30-year horizon
- A specific Social Security claiming strategy modeled against the individual’s actual earnings record, rather than a generic assumption about the “right” age to claim
- A comprehensive financial analysis that accounts for both federal and island-specific tax treatment of every income source expected in retirement, not just the largest or most obvious one
Read Also: Act 22 vs. Act 60: What Changed for Puerto Rico Investors
Building the Habit of an Annual Check-In, Not Just a One-Time Fix
None of these eight mistakes get solved permanently by a single conversation or a single year of corrected contributions. The 50s span roughly a decade, and circumstances, income, health, family obligations, tax law itself, shift meaningfully within that window, as the mid-2026 catch-up contribution change makes clear. Treating retirement planning as an annual check-in rather than a project completed once and set aside catches these shifts while there’s still time to adjust, rather than discovering a mismatch between the plan and reality only when retirement itself is already underway.
What an Annual Review Should Actually Cover
A short list of items deserves a fresh look each year rather than being set once and forgotten:
- Whether current contribution levels still reflect the maximum catch-up limits available, since these figures adjust nearly every year
- Whether recent income changes affect eligibility for Roth versus pre-tax catch-up contributions under the new high-earner rule
- Whether family circumstances, an aging parent, a child’s education costs, a health change, have shifted enough to warrant adjusting the broader plan rather than just the numbers on a single account statement
Turning the 50s Into the Decade That Decides the Outcome, Not the Decade That’s Wasted
None of these eight mistakes are exotic or hard to understand once they’re named directly, and none of them require a financial background to address. What they require is treating the 50s as the decade where the actual plan gets built, rather than the decade where good intentions quietly substitute for one. The confidence gap showing up in national surveys reflects real uncertainty, but it isn’t unfixable, and the tools available this decade specifically, catch-up contributions, a clear-eyed look at healthcare costs, an honest conversation with aging parents, and a plan built around real numbers rather than averages, exist precisely because this age carries both real risk and real opportunity.
Disclaimer: This article is for educational purposes only and does not constitute individualized financial, tax, or legal advice. Consult a licensed professional regarding your specific circumstances.